
Saturday, June 20, 2020

Tuesday, March 3, 2020
5 Golden tips to increase your CIBIL Credit Score
5 Golden tips to increase your CIBIL Credit Score

First, understand - what is CIBIL & Credit Score.
TransUnion CIBIL Limited is Credit Information Company;
that takes information from Banks and Financial Institutions (FIs) on Monthly basis and;
prepares Credit Information Report (CIR),
Basis the CIR, a Credit Score is generated.
This Credit Score is called as CIBIL Score/ Credit Score.
What Credit Score shows?
Credit Score is 3 (three) digit score,
Range - 300 to 900
 Higher, the BetterGreen zone shows welcome action/ comfort by Banks. Credit Score more than 750 are considered good for giving loan by Banks.


Saturday, February 22, 2020
Birthday Rule for Senior Citizens and Very Senior Citizens under Income Tax Act.
Birthday Rule for Senior Citizens and Very Senior Citizens under Income Tax Act
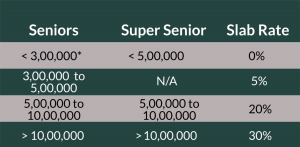
Income upto Rs. 3,00,000/- is exempted under Income Tax Act for Resident Senior Citizens.
Similarly, Income upto Rs. 5,00,000/- is not taxable for Resident Very (Super) Senior Citizen.
Individual,who is of the age of 60 years or more, but less than 80 years at any time during the previous year/financial year is Senior Citizen.
In the same line, Individual, who is of the age of 80 years or more, at any time during the previous year/financial year is very/super Senior Citizen.
For example:
Suppose today is January 01, 2020), the previous year/ financial year is 2019-20 (assessment year will be 2020-21)[assessment year is always following the previous year]. If an individual's 60th birthday falls in any time during financial year 2019-20, his income upto Rs. 3,00,000/- is exempted from Income Tax.
Similarly, If any individual has celebrated his 80th birthday, any time during the previous year 2019-20, the income tax rate is relaxed rate (upto Rs. 5,00,000/-).
If 60th or 80th birthday falls on 1 April. what will happen?
because, from 1st April, one previous years/financial year ended and next previous year/financial year starts.
For example:
In previous year/financial year 2019-20 (from 1st April 2019 to 31st March 2020).
Mr. A's birthday was in 2nd April 2019 - He is Senior Citizen for Income of previous year/financial year 2019-20.
(Rule - Individual,who is of the age of 60 years or more, but less than 80 years at any time during the previous year/financial year is Senior Citizen)
But, if Mr. A's birthday falls on 1st April 2020 - Should Mr. A is eligible for Senior Citizen's benefits in previous year 2019-20? (whereas previous year 2019-20 has ended on 31st March 2020 - and not on 1st April 2020)
Income Tax Act provided clarification regarding attaining the age of 60/80 year, for individuals, whose birthday fall on 1st April every year.A person born on 1st April would be considered to have attained a particular age on 31st March, the day previous the anniversary of his birthday.
Hence, in the above case, Mr. A would be eligible for getting the benefits of Senior Citizen in the previous year 2019-20 itself.
Therefore, a resident individual whose 60th/80th birthday fall on 1st April 2020, would be treated as having attained the age of 60/80 years in the previous year 2019-20, and would be eligible for higher basic exemption limit of Income Tax of Rs. 3,00,000/- and Rs. 5,00,000/- respectively, in computing the tax liability for previous year/financial year 2019-20 (assessment year 2020-21).

@FinanceSikho
Thursday, February 20, 2020
Taxation of Gift
Taxation of Gift
 |
| Gift and Income Tax in India |
As a general rule, Gift exceeding Rs. 50,000/- is taxable under - Income from other sources.
Now, what Income Tax Act says about the Gifts:-
- If you are an Individual OR Hindu Undivided Family (HUF);
- You have received any Gift (as explained below), during the previous year;
- Without any consideration;
- and if the aggregate value of such gift is more than Rs. 50,000/- (in previous year);
- The whole sum of money is chargeable to Tax.
(applicable on and after 01.10.2009)
What can be the type of Gifts?
1. Money(may be in the form of cash, cheque, draft etc.)
2. Immovable properties (land, building or both)
3. Prescribed movable property viz. shares/securities, jewellery, archaeological collections, drawings, paintings, sculptures or any work of art and bullion.
So, not other movable property, for example TV, AC, fridge are not coming under this provisions.
Aggregate or Individual Gifts
If one gift is not more than Rs.50,000/- but if the aggregate value of all sums received during the one financial year exceed Rs. 50,000/- then the whole sum will be taxable.
For example:If gift received in the form of cash of Rs. 49,000/- then it will not be taxable.
But If gift received in the form of cash is Rs. 51,000/- then the whole sum of money (Rs. 51,000/- will be taxable under Income from Other Sources).
What are the exception to this rule?
(Such exception is applicable to all type of Gifts prescribed above)
In the following cases, gifts received in excess of Rs. 50,000/- is not taxable:
-If received from any relative to an Individual and from any member of HUF to HUF,
(Who are 'relative')
(i) spouse of the individual;
(ii) brother or sister of the individual;
(iii) brother or sister of the spouse of the individual;
(iv) brother or sister of either of the parents of the individual;
(v) any lineal ascendant or descendant of the individual;
(vi) any lineal ascendant or descendant of the spouse of the individual;
(vii) spouse of the person referred to in clauses (ii) to (vi);
Gift received from Friend is Taxable.
- On the occasion of ONLY marriage of the Individual,Gift received from Friend is Taxable.
It means gifts received on the occasion of Birthday, Anniversary, other functions are Taxable.
- Under a will/ by way of inheritance,
- in contemplation of death of the payer or donor
[gift of property made by its owner who expects to die shortly, the gift being motivated solely by the thought of his or her demise.]
- from a local authority, any fund, foundation, university, other educational institution, hospital or other medical institution, any trust or institution.(Section 10 of Income Tax Act specifies such institutions,fund etc.)- from an Individual by a trust created or established solely for the benefit of relative of the Individual. (applicable if the property is received on or after 01 April, 2017).
In respect of immovable properties (being land, building or both)
If an Individual or HUF receives
|
any person receives
|
on or after 01.10.2009 but before 01.04.2017
|
After 01.04.2017
|
in any previous year
| |
from any person or persons
| |
any immovable property(being land or building or both)
| |
without consideration, the stamp duty value of which exceeds Rs. 50,000 then the stamp duty value shall be chargeable to tax.
| |
for a consideration, if stamp duty value exceeds the amount of consideration and the difference between stamp duty value and consideration is more than Rs. 50,000, then such difference is chargeable to tax. (applicable from A.Y 2014-15 to A.Y 2018-19).
| |
for a consideration, if stamp duty value exceeds 105% of the amount of consideration and the difference between stamp duty value and consideration is more than Rs. 50,000, then such difference is chargeable to tax. (applicable from A.Y 2019-20)
| |
But, here the limit of Rs. 50,000/- is for transaction wise and NOT THE AGGREGATE VALUE. If 2 properties were received in one financial year and stamp duty value of each property is not exceeding Rs. 50,000/- then nothing will be taxable. (the aggregate value can be more than Rs. 50,000/-).
Examples of movable property received as gift
Suppose, Mr. H received in FY 2019-20 shares of Rs. 25,000/- from his close friend and Jewellery of estimated value of Rs. 55,000/- (fair market value is Rs. 57,000/-), as gifts; Now what is taxable ?
(The fair market value will be taxable)- Rs. 82,000/- will be taxable in the hand of Mr. H in FY 2019-20.
Suppose, Mr. H received in FY 2019-20 drawings after paying a sum of Rs. 49,000/- to his close friend. The fair market value of the drawing is Rs. 52,000/- Now what is taxable ?
Nothing is chargeable to tax, being the difference between fair market value and consideration paid is not more than Rs. 50,000/-
Suppose, Mr. H received in FY 2019-20 furniture after paying a sum of Rs. 49,000/- to his close friend. The fair market value of the furniture brought is Rs. 1,00,000/- Now what is taxable ?
Noting will be taxable, as furniture is not the prescribed movable asset.
What will be the case if gift/money/movable assets is received by a non-resident?
for answer- Stay tuned....
****************************************************************
Wednesday, February 5, 2020
What is NIFTY 50 and How it is calculated?
What is NIFTY 50 and How it is calculated?

- National Stock Exchange Fifty (NIFTY 50).
- NIFTY 50 is an equity benchmark index which was introduced by National Stock Exchange (NSE).- NIFTY 50 index is 50 well diversified company’s stock that reflect the overall market condition.
Now the biggest question-Which stock is eligible for selection into NIFTY 50 index?
Eligibility:
-Minimum 6 months listing history (company comes out
with an IPO, and fulfill normal eligibility criteria for the index for 3 month
is also eligible).
-Company should allow trading in
F&O segment.
-The stock should trade at an
average impact cost of 0.50% or less
during the last six month for 90% of the observations, for the basket size of
Rs. 10 crore.
What is Impact Cost:
In mathematical terms Impact Cost is the percentage mark up
observed while buying / selling the desired quantity of a stock with reference
to its ideal price (best buy + best sell) / 2.
Example:
Suppose you want to buy 1500 shares and the available bids in the
market are as under:
Buy qty
|
Buy price
|
Sell qty
|
Sell price
|
1000
|
98
|
1000
|
99
|
2000
|
97
|
1500
|
100
|
1000
|
96
|
1000
|
101
|
To buy 1500 shares
Ideal Price = 99+98/2 = 98.50
Actual Buy Price = [(1000*99)+(500*100)]/1500 = 99.33
Impact Cost = (99.33-98.80)/ 98.50 = 0.84%
Sector representation in NIFTY 50
FINANCIAL SERVICES
|
41.50
|
ENERGY
|
13.66
|
IT
|
13.17
|
CONSUMER GOODS
|
11.60
|
AUTOMOBILE
|
5.66
|
CONSTRUCTION
|
3.42
|
METALS
|
2.95
|
TELECOM
|
2.67
|
PHARMA
|
2.17
|
CEMENT & CEMENT PRODUCTS
|
1.63
|
FERTILISERS & PESTICIDES
|
0.59
|
SERVICES
|
0.58
|
MEDIA & ENTERTAINMENT
|
0.41
|
Top Stocks with weightage:
Company
|
Weight (%)
|
10.73
|
|
9.23
|
|
8.42
|
|
6.87
|
|
5.75
|
|
4.58
|
|
4.42
|
|
4.15
|
|
3.42
|
|
3.28
|
Portfolio Characteristics:
Methodology
|
Free Float Market
Capitalization wherein the level of index reflects the free
float market capitalisation of all stocks in Index.
|
No. of Constituents
|
50
|
Launch Date
|
April 22, 1996
|
Base Date
|
November 03, 1995, which marks the completion of one year of operations of
NSE's Capital Market Segment.
|
Base Value
|
1000
|
Calculation
Frequency
|
Real-Time Daily
|
Index Rebalancing
|
Semi-Annually, January
31 and July 31 of each year
|
****************************************************************